 Arabic (Saudi)


17 Oct 2026
Share :
Global Sugar Market Update October 2026 - Price & Deficit Trends | AgriGuru Online
Description:
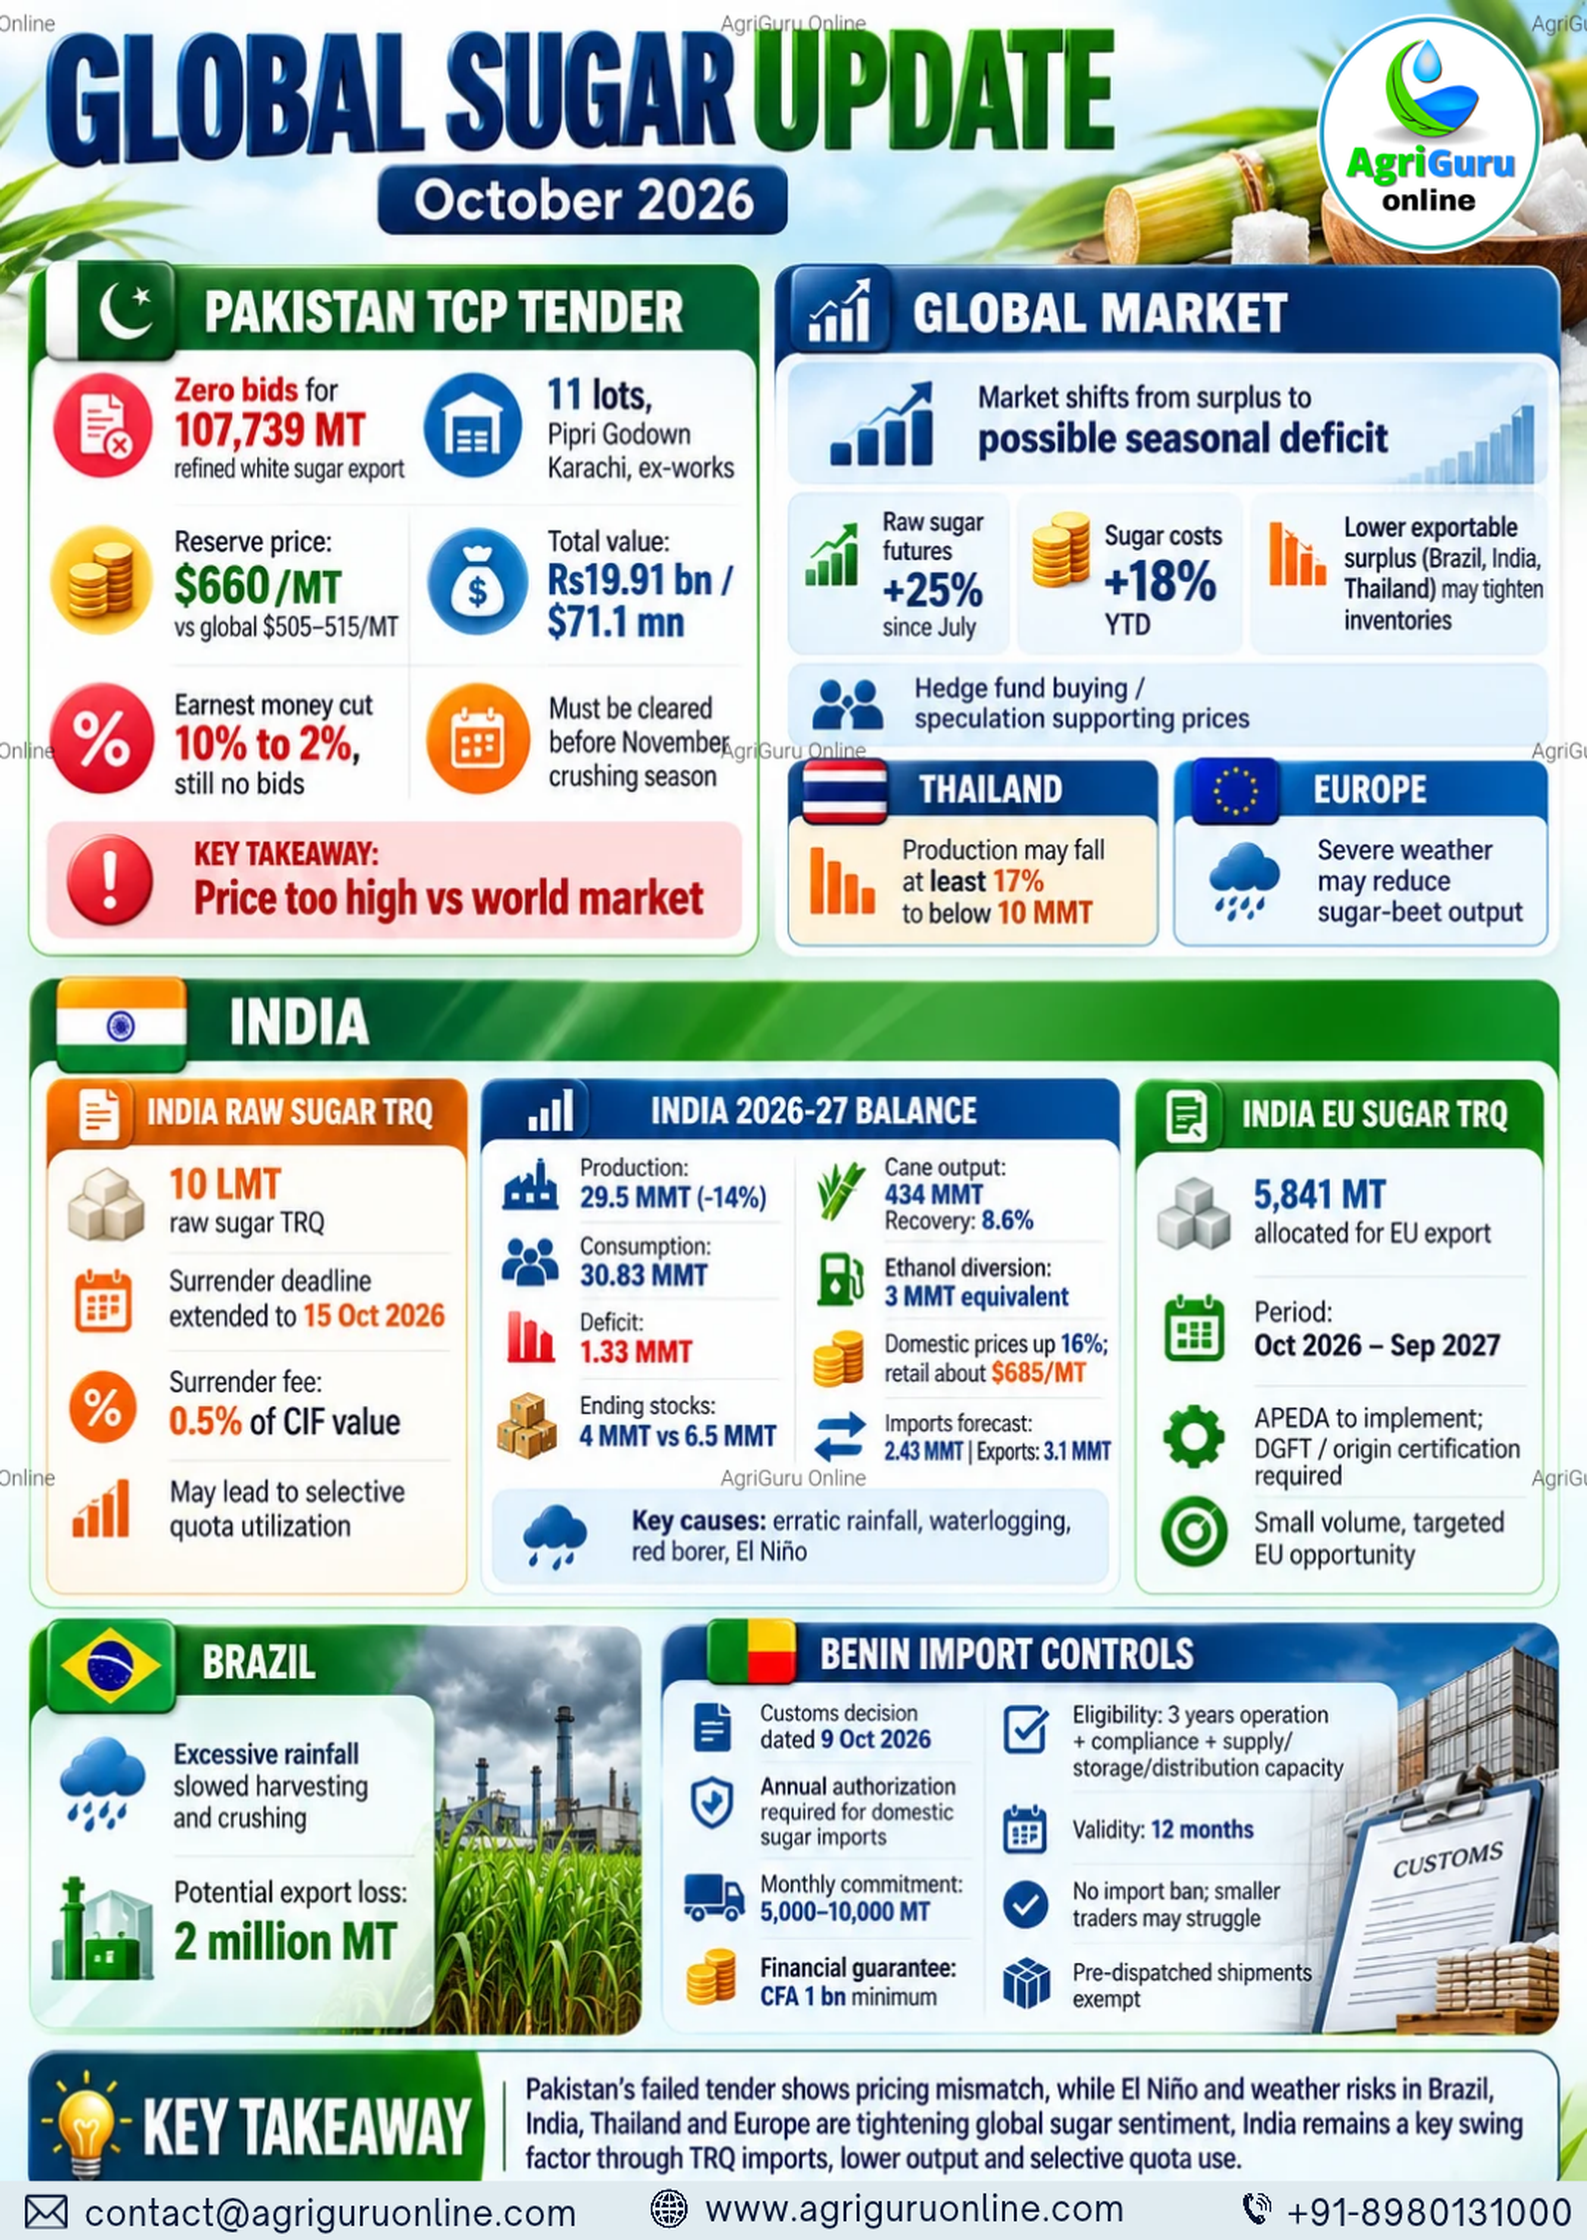
The global sugar market is experiencing a structural pivot from a surplus toward a seasonal deficit, driven by weather disruptions across major producing nations, speculative fund buying, and tightening exportable surpluses.
Key Regional & Market Highlights (October 2026):
- Global Market Overview: Raw sugar futures have surged +25% since July, with overall sugar costs up +18% YTD. Reduced exportable surpluses from Brazil, India, and Thailand are tightening global inventories.
- Pakistan TCP Export Tender: The TCP tender for 107,739 MT of refined white sugar export (11 lots ex-works Pipri Godown, Karachi) received zero bids despite cutting earnest money from 10% to 2%. The official reserve price of $660/MT ($71.1 mn total) proved too high compared to the global market rate of $505–$515/MT.
- India Sugar Balance (2026-27): Production is estimated at 29.5 MMT (-14% YoY) due to erratic rainfall, waterlogging, red borer, and El Niño. With consumption at 30.83 MMT, India faces a 1.33 MMT domestic deficit. Ending stocks are projected to drop to 4 MMT (vs 6.5 MMT). Ethanol diversion stands at 3 MMT equivalent. Additionally, the Raw Sugar TRQ surrender deadline was extended to Oct 15, 2026 (0.5% CIF fee), while 5,841 MT was allocated for the EU Sugar TRQ (Oct 2026 – Sep 2027).
- Brazil & Thailand: Heavy rainfall in Brazil has slowed harvesting and crushing, risking a potential export loss of 2 million MT. Thailand's production is projected to fall by at least 17% to below 10 MMT.
- Benin Import Controls: Following a customs decision on Oct 9, 2026, Benin implemented strict annual import authorizations, requiring a minimum CFA 1 bn financial guarantee and monthly commitments of 5,000–10,000 MT, impacting smaller traders.